THE LONG END OF THE YIELD CURVE
Higher long-term yields are changing the trade-offs between income, price sensitivity and the obligations a portfolio must support.
Higher bond yields can be welcome news for investors seeking income, but they can also make borrowing more expensive. Someone approaching retirement may find more attractive income opportunities in fixed income, while a homeowner renewing a mortgage or a business owner refinancing debt may face higher costs. For investors managing both assets and financial obligations, these developments can have different effects.
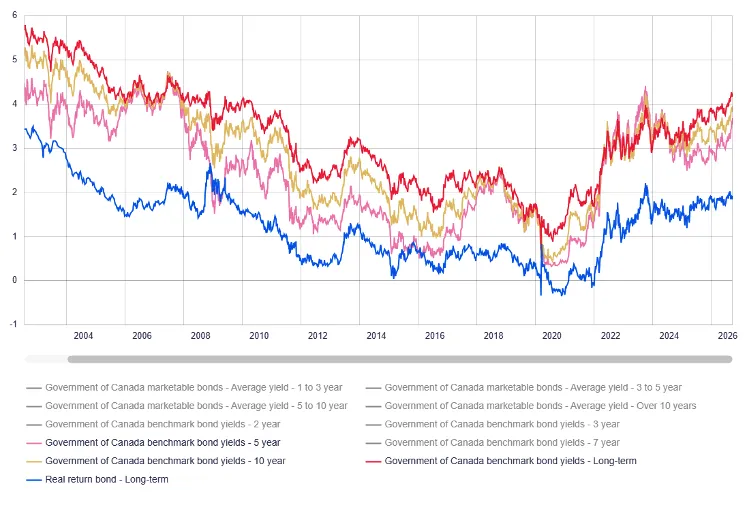
Long-term government bond yields in Canada and the United States have risen to levels not seen for many years. On September 25, 2026, the U.S. Treasury curve closed at 4.98% for five years, 5.17% for 10 years and 5.49% for 30 years.¹ Canadian benchmark yields for the same time period were 3.69% for five years, 3.97% for 10 years and 4.27% for the long-term benchmark.² (see Chart)
High yields can improve the income available from high-quality fixed income products. However, their broader implications depend on an investor’s borrowing needs, existing investments and financial objectives.
Exhibit: Average Yields For Selected Government Of Canada Marketable Bonds: 2004 – 2026
Source: CanDeal Data and Analytics (CanDeal DNA) and Bank of Canada
https://www.bankofcanada.ca/rates/interest-rates/canadian-bonds/
Why Long Rates Move Differently
Central banks influence short-term interest rates, but longer-term bond yields are determined by market conditions. Investors buying bonds that mature many years from now consider factors such as future inflation, economic growth and the additional return they may require for committing their money over a longer period. As a result, longer-term yields don’t necessarily move in the same direction, or at the same pace, as central bank policy rates.
The supply of bonds also matters. Large fiscal deficits mean governments must issue more debt, requiring investors to absorb additional bonds. Corporate borrowers compete for the same capital, adding to the financing demands.
The Effect Beyond Bonds
When yields rise, the price of an existing fixed-rate bond generally falls because newly issued securities offer more attractive income. The effect is greater for longer-maturity bonds, which have more payments exposed to a change in market rates.
Higher yields also change the economics of borrowing. Mortgages, investment loans, business credit and commercial real estate financing may become more expensive to renew. Companies facing higher borrowing costs might delay projects or demand a higher expected return before investing. And assets purchased with leverage can feel the effect from both lower valuations and more costly debt.
Consider someone approaching retirement who holds bonds for income and has a mortgage coming up for renewal. Higher yields provide an opportunity to earn more income from new fixed-income investments, but the cost of renewing the mortgage also rises. The overall effect on their financial position depends on both sides of that equation, not simply the performance of their bond holdings.
If you own businesses, real estate or private investments alongside marketable securities, the impact of higher rates can extend well beyond your bond holdings. Changes in interest rates can affect investment income, asset valuations and borrowing costs simultaneously, making it important to understand how these exposures interact.
The Role of Fixed Income in Your Portfolio
Capital reserved for a near-term obligation serves a different purpose from assets intended to generate income over decades or provide balance during equity market declines. The role of fixed income within a portfolio therefore depends on the investor’s financial objectives, income requirements and time horizon.
Shorter-maturity bonds generally experience smaller price fluctuations when interest rates change and can provide access to capital as they mature. However, they also carry reinvestment risk; for example, if yields have declined by the time a bond matures, the proceeds may need to be reinvested at a lower rate. Longer-maturity bonds can secure income over an extended period and benefit from lower yields, although their prices are more sensitive to changes in interest rates.
Balancing these trade-offs involves holding bonds with different maturities, depending on anticipated cash needs, investment objectives and the sensitivity of other holdings to interest rates. Upcoming mortgage renewals, major purchases or retirement income requirements further influence how fixed income fits within a broader financial plan.
Another consideration is the timing of bond maturities relative to anticipated expenses. A portfolio designed to provide income over many years looks different from one intended to fund a significant expense in the near future. Understanding when capital may be needed helps put the trade-offs between income, price fluctuations and access to funds into perspective.
Higher yields have made fixed income more attractive for investors seeking income, but the benefits cannot be considered in isolation. Borrowing costs, anticipated expenses and the timing of future income needs all influence how bonds contribute to a financial plan. These are useful considerations to explore with us as your investment advisor, particularly when financial circumstances or investment objectives are changing.
Sources
1. U.S. Department of the Treasury, Daily Treasury Par Yield Curve Rates. Accessed September 25, 2026
2. Bank of Canada, Selected Bond Yields. Accessed September 25, 2026